For most of the last century, people assumed that the logic of energy infrastructure was predetermined: richer countries would build the networks, while others would wait and eventually catch up. The US and Europe established the standards, paid for the power plants, and constructed the transmission lines. The developing countries hoped someday to be able to join the ranks of energy-rich countries. Today, the rise of the smart grid is changing this dynamic. This scenario is outdated, and even reversed.
Nowadays, the countries that are advancing their technologies and implementing smart grids with the greatest speed are not limited to Washington or Brussels. While in the US, 2,600 gigawatts worth of clean energy projects remain stuck on connection queues, double that of all installed energy sources in the country, China, India, Africa, and Brazil are independently writing a new book of rules for the industry.
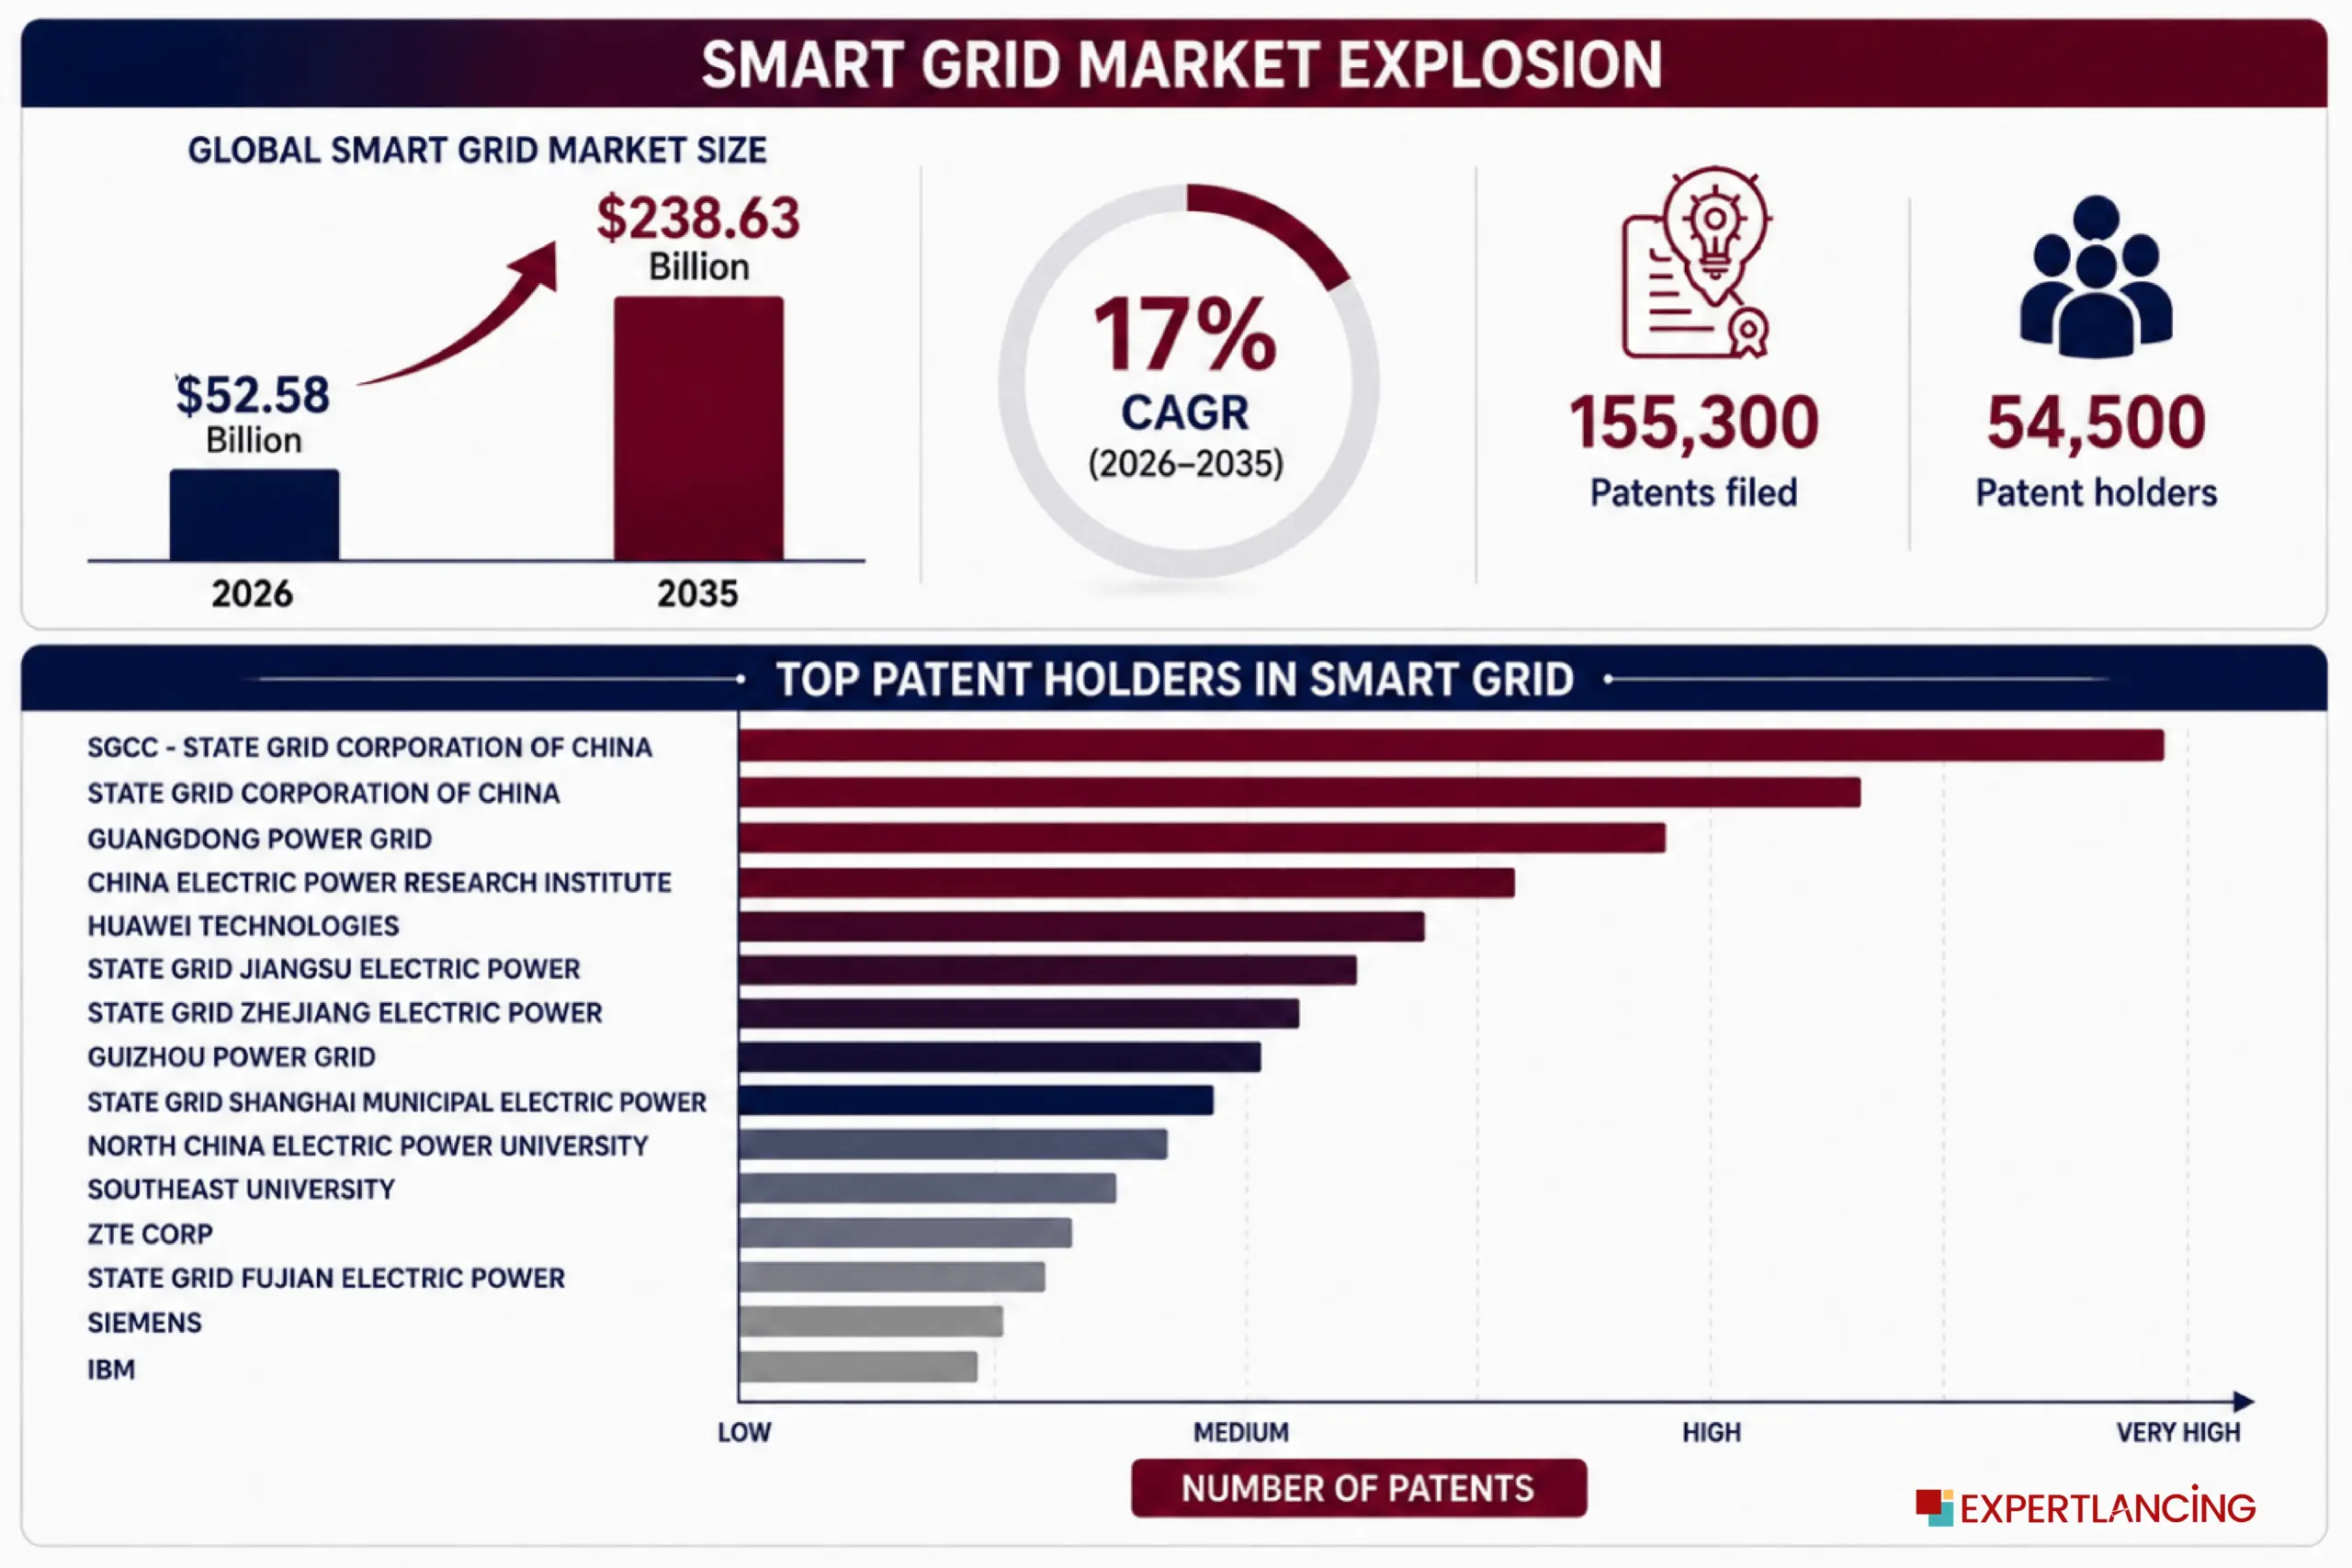
The worldwide smart grid market, estimated at around $52.58 billion in 2026, is projected to grow up to $238.63 billion by 2035, with a CAGR of 17%. The level of innovation in the industry is very high: 155,300 patents have been filed in the smart grid area by 54,500 patent holders, and the rate of patent filings per year is around 6.92%. Notably, China ranks first globally in smart grid patent filings, reflecting its strong focus and leadership in this sector. As the industry evolves, the challenge is no longer just building megawatts; it is managing variability at scale.
The West’s Grid Is Trapped by Its Own Success
In the paradoxical situation in which the Western world finds itself regarding energy, there lies an ironic twist. While it is precisely those countries that have developed and sustained the present electrical infrastructure, their dependence on it now limits them in ways never before seen.
As shown in the report entitled ‘Electricity 2026’ by the International Energy Agency (IEA), there are already 2,500 gigawatts of renewable energy projects waiting in line for grid connections worldwide: 2,600 gigawatts in the US and almost 1,700 gigawatts in 16 European countries. The primary bottlenecks are not technological limitations but regulatory and administrative challenges. Lengthy permitting processes and resistance related to land use have emerged as major barriers to expanding grid infrastructure in both regions.
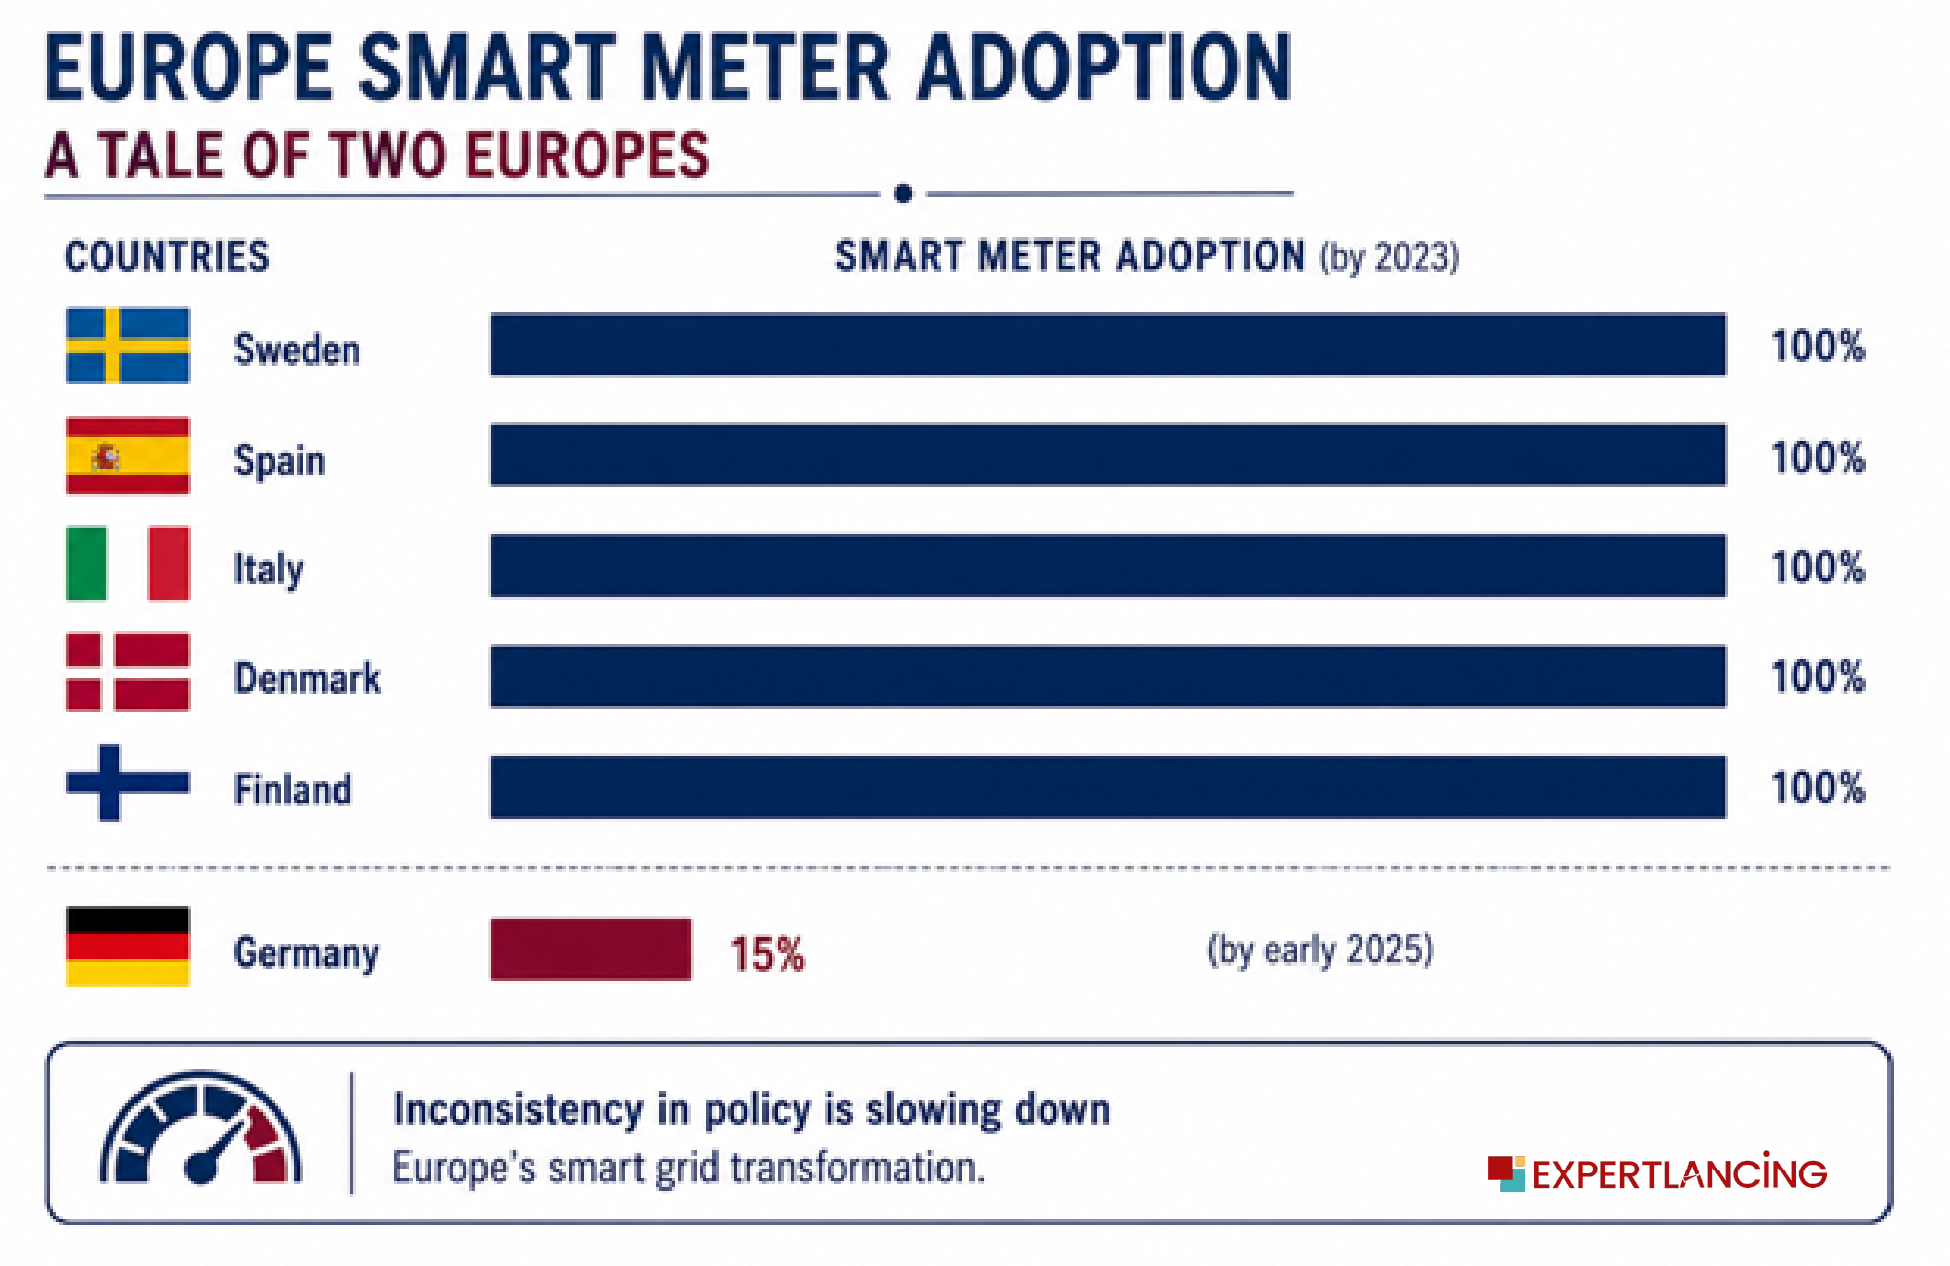
Inconsistency in Europe adds to the situation. Adoption statistics for smart grids in Europe, based on the IIIEE Energy Blog (April 2026), show that while countries like Sweden, Spain, Italy, Denmark, and Finland installed all of their smart meters by 2023, the German government implemented its national mandate in the same period but managed only 15% adoption until early 2025. Additionally, the worldwide expenditure on grids was estimated at over $470 billion in 2025, of which the US invested $115 billion. Nonetheless, despite the massive investments, there is no acceleration in deployments.
India: The World’s Most Ambitious Grid Transformation
For the first time in history, in January 2026, non-fossil-based sources of energy, which include 263.2 GW of renewable power and 8.78 GW of nuclear power, account for over 52% of India’s total installed capacity of 520.5 GW. “Breaking through 50 percent fundamentally changes how the grid needs to work,” said Frost & Sullivan analysts in an April 2026 report. “The task isn’t simply to build megawatts anymore. It’s managing variability at scale.”
A total of 47.6 million smart meters have been installed in India as part of its National Smart Grid Mission by the end of 2025. 29 million meters were rolled out in just five months up to May 2025. The smart meters allow for prepaid energy management, energy accounting at the feeder level, real-time energy usage data, and remote fault detection using SCADA/DMS.
The Indian grid modernisation market had a market value of US$ 1.51 billion in 2025 and is expected to reach US$ 7.65 billion by 2034 at a CAGR of 19.78%, which is nearly thrice the global smart grid market CAGR.
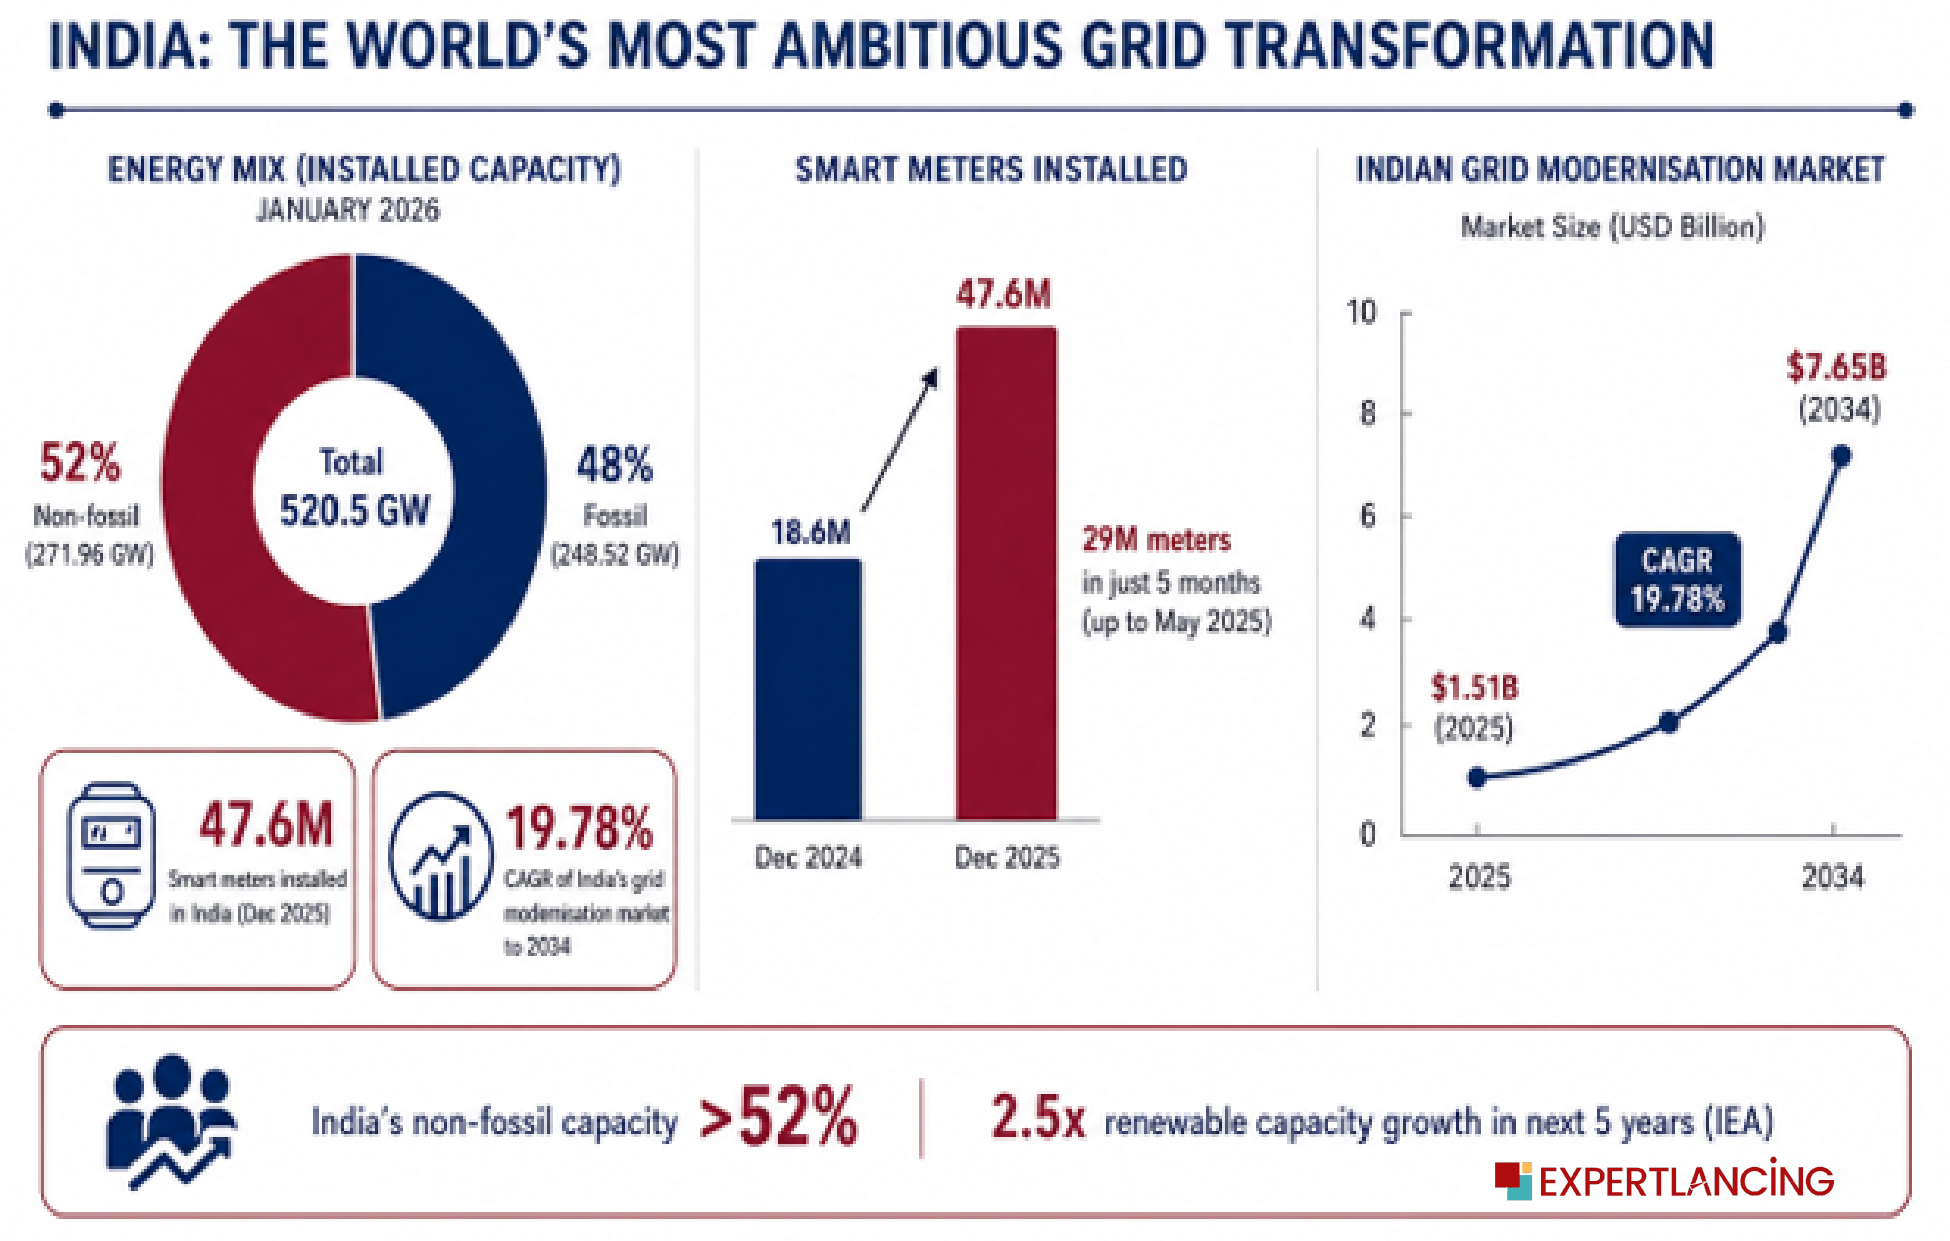
The Renewables 2025 report by the International Energy Agency (IEA) indicates that India will be able to become the second-largest growth market for renewables globally with a total capacity to increase by 2.5 times in the next five years.
The Indian grid modernization market has a CAGR of 19.78%, which is nearly thrice the global market CAGR. India has deployed 47.6 million smart meters, while renewable sources now account for more than 52% of its power capacity.
China – The World’s Largest Grid Buildout in History
China is implementing the largest grid development project in history.
In January 2026, the State Grid Corporation of China announced plans to invest RMB 4 trillion in fixed assets during the 15th Five-Year Plan (2026–2030). This represents a 40% increase over the previous five-year period.
State Grid is to intensify its efforts to develop ultra-high voltage DC transmission corridors. These corridors will transmit renewable energy from huge solar power plants and wind farms in arid deserts and the Gobi region. They will carry this energy to coastal cities with many factories, thousands of kilometres away. The inter-regional transmission capacity will be increased by over 30% from the end of the previous plan period.
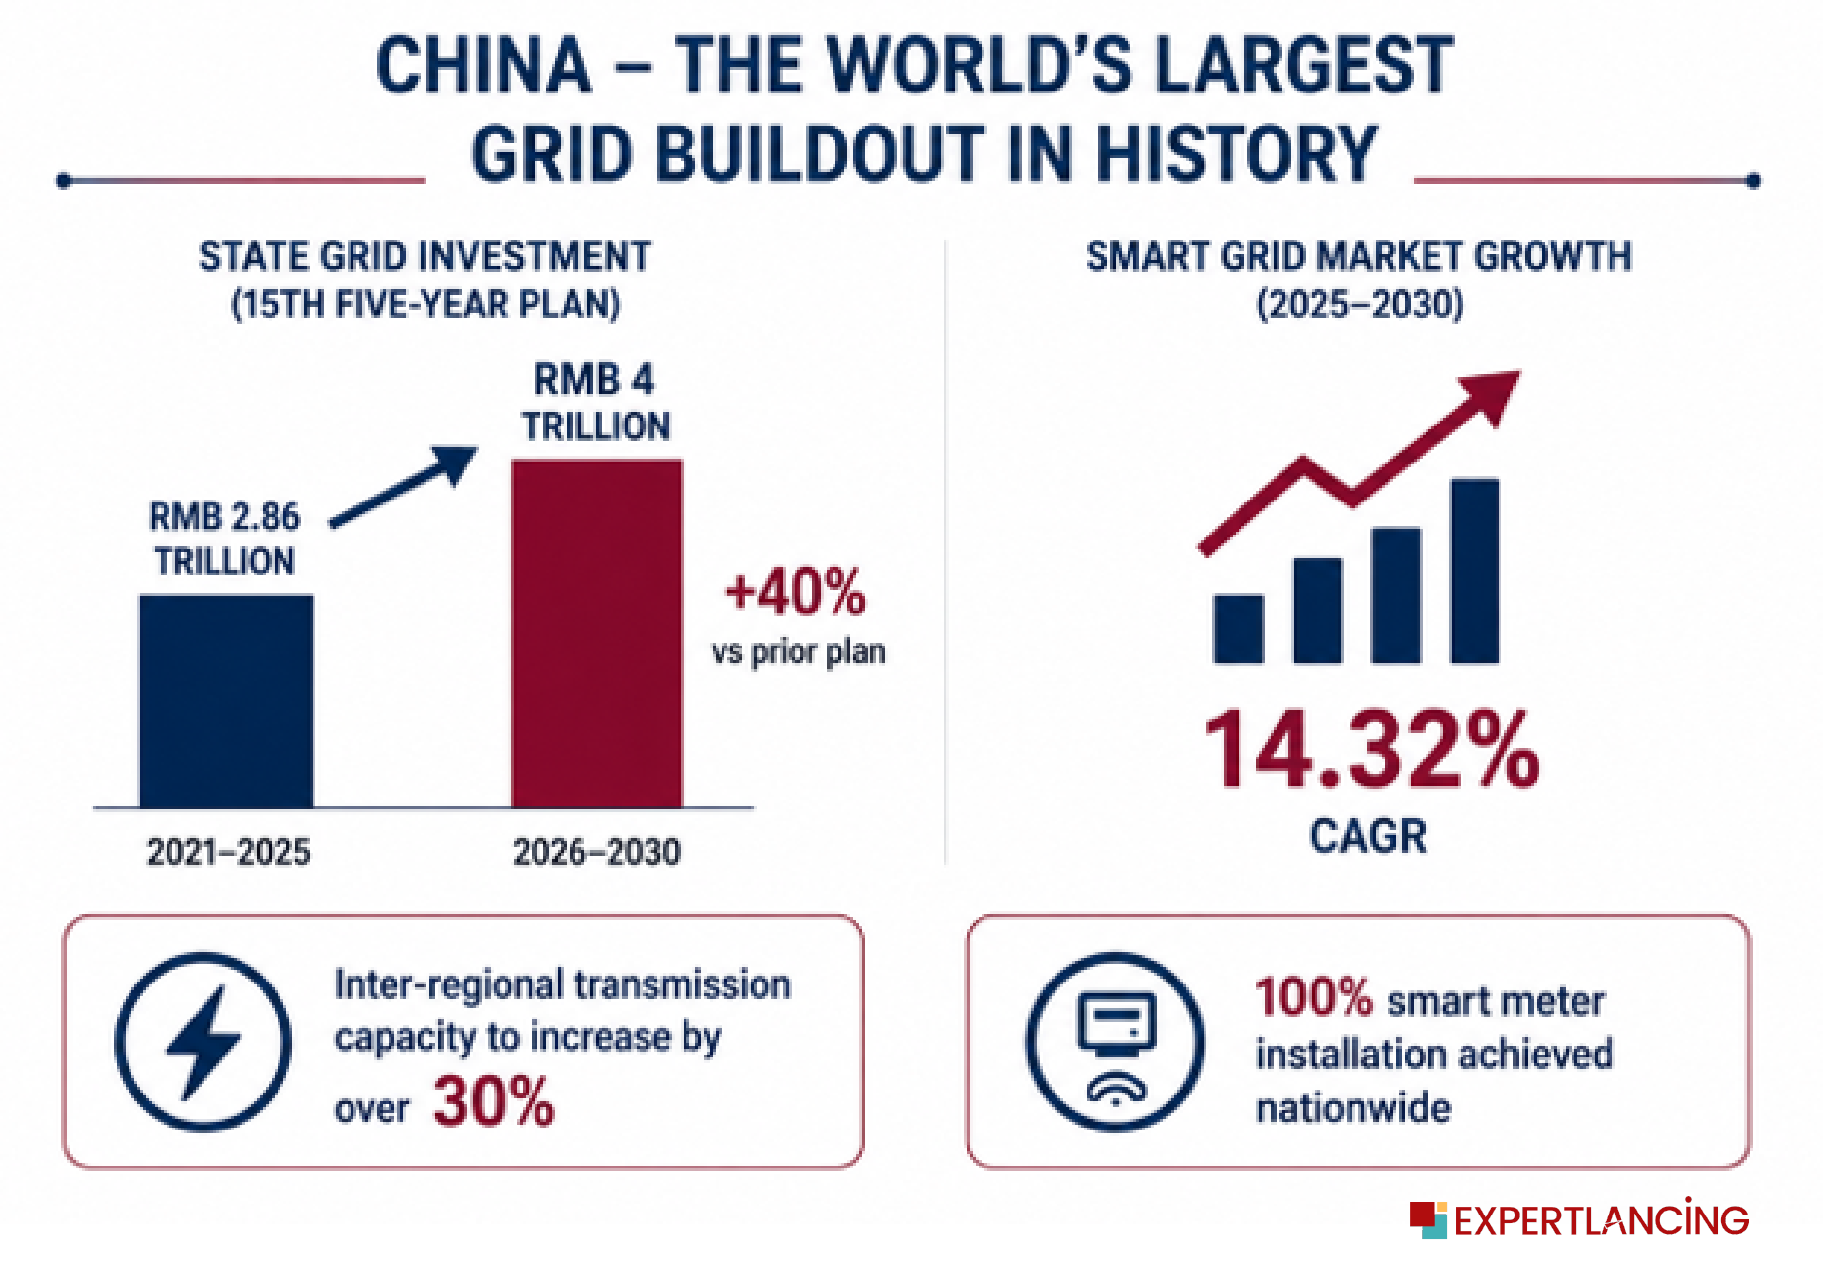
Analysts project that China’s smart grid network market will grow by 14.32% annually. This will enable the China Electricity Council’s target of total investment in smart grids to amount to CNY 4 trillion. China has also succeeded in making sure that it achieves 100% installation of smart meters all over the country; something that countries like Germany, having one of the biggest economies in Europe, have yet to achieve.
Africa and Latin America – Leapfrogging and Scaling
Africa and Latin America provide examples of two different but equally influential trajectories of grid innovation. The continent of Africa is skipping the grid paradigm entirely. In an article published in Science magazine (July 2025), scientists describe the requirements for a successful technological leapfrog. First, developed countries must prove the technology’s effectiveness and demonstrate its success. Second, the technology should have similar or even better performance than the existing technology. Third, it should make it possible to circumvent infrastructure. Distributed solar energy and smart grids meet all these requirements.
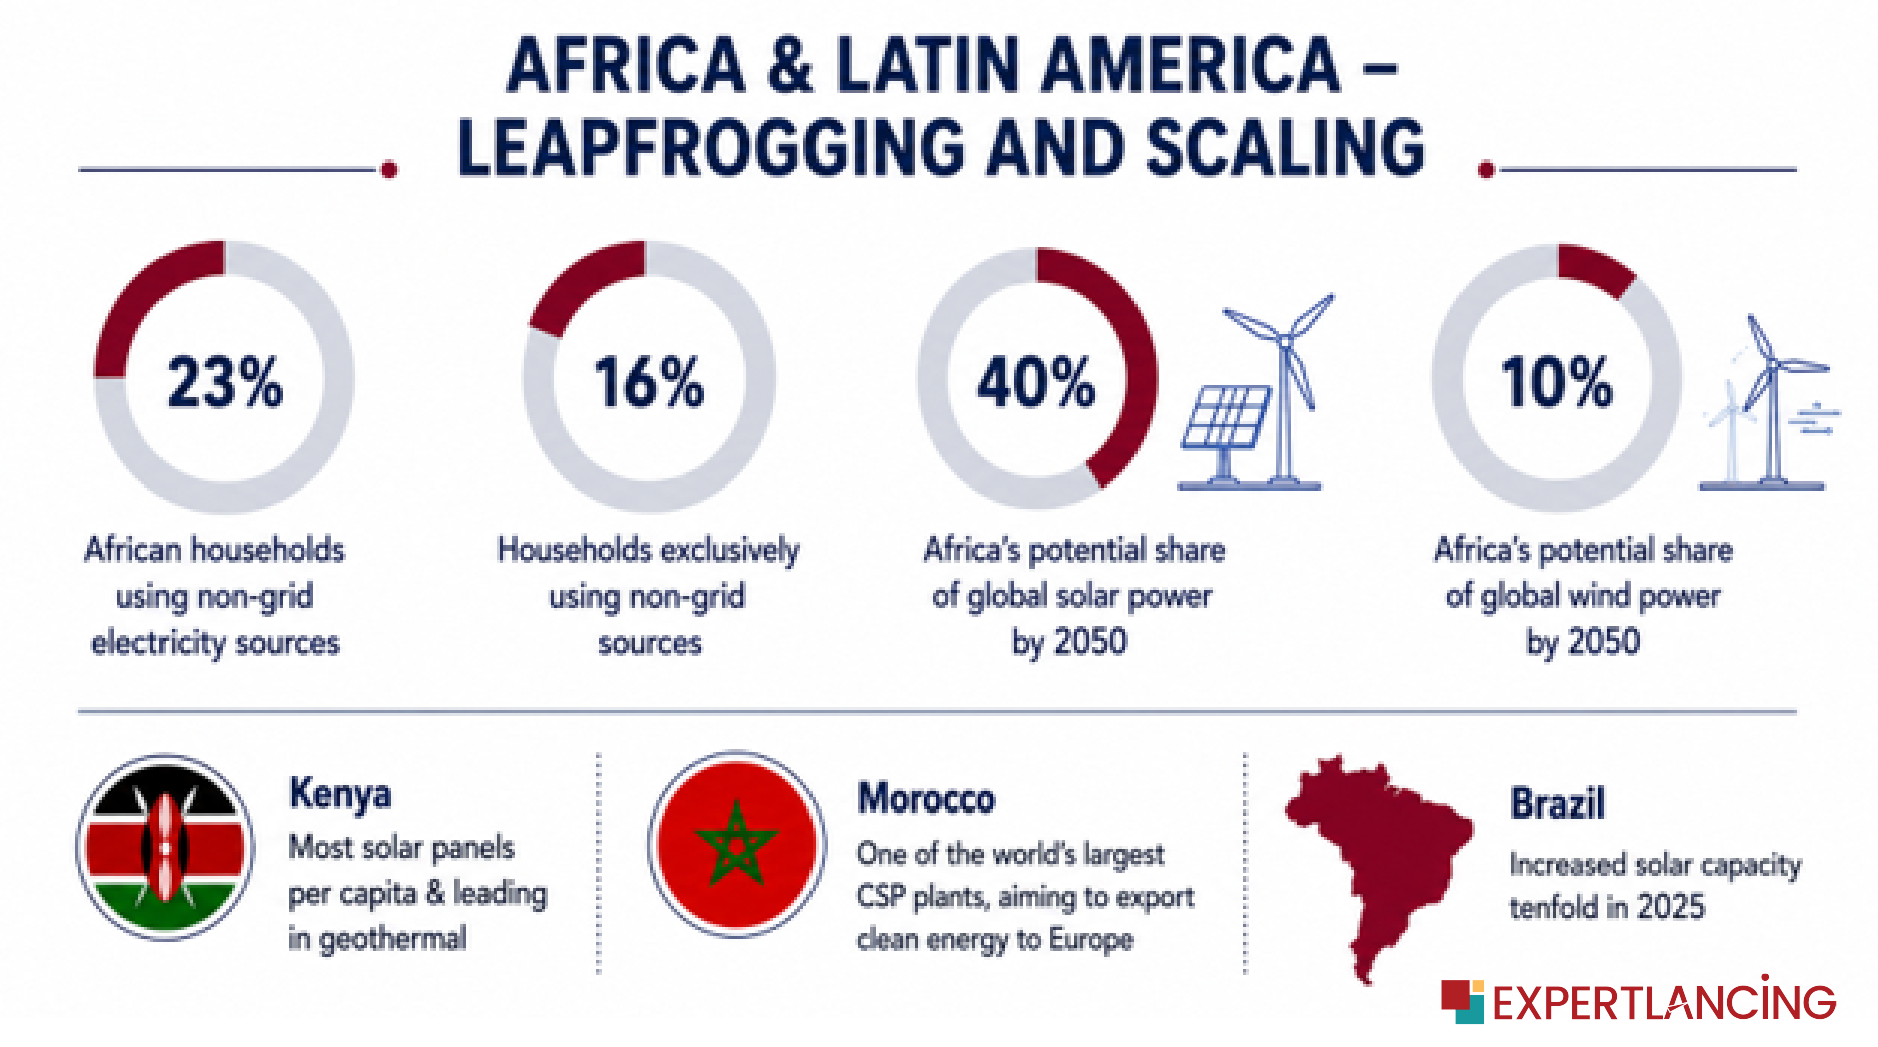
Kenya has the highest number of solar panels per capita of any country. It was also the first African nation to utilise geothermal energy. By 2040, geothermal energy will constitute 50% of the total energy consumed in Kenya. Morocco has built one of the world’s largest concentrating solar power stations. It aims to become a clean energy exporter to Europe. According to Afrobarometer surveys conducted across 34 African nations, 23% of African households currently obtain electricity from non-grid sources. Of these, 16% rely exclusively on non-grid sources. The continent has the capacity to generate 40% of global solar power and 10% of wind power by 2050.
Why Developing Nations Hold the Structural Advantage
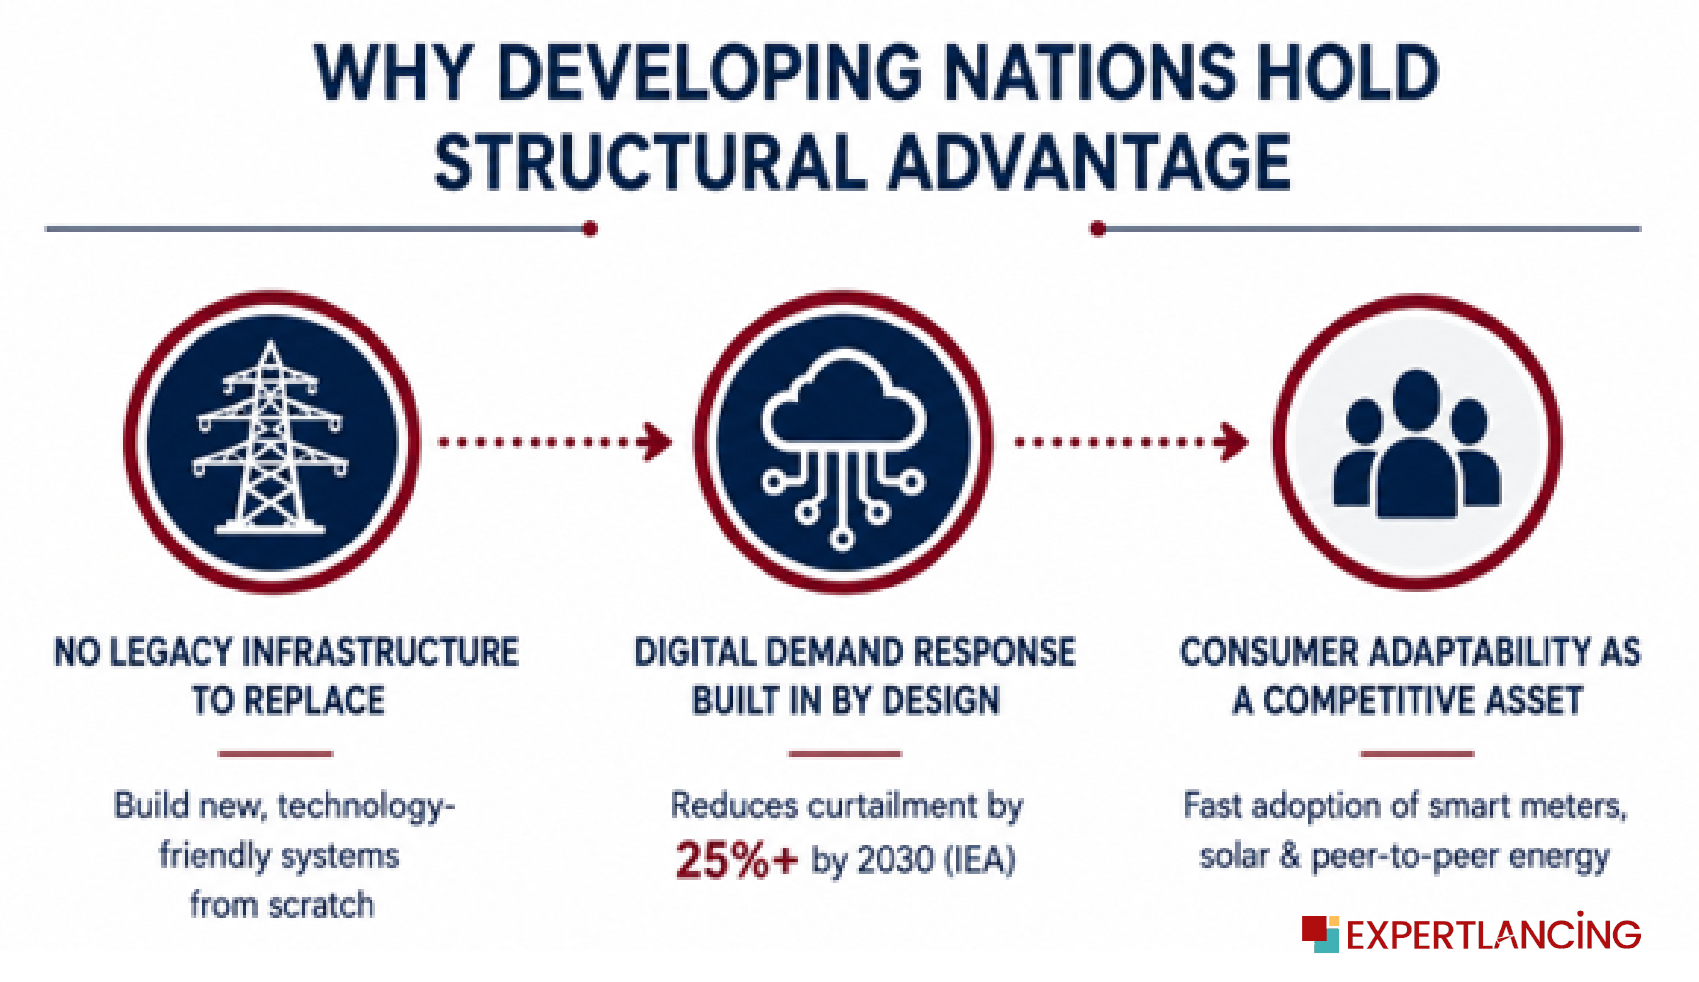
Emerging countries modernise their grids more efficiently by leveraging three enduring structural advantages. Traditional grid systems often lack these advantages, even when they have sufficient funding.
- No Legacy Infrastructure to Replace: In the US grid, there is some infrastructure from the 1950s and 1960s that needs upgrading. This would involve coordinating with utilities, compensating property owners, environmental impact assessments, and maintaining grid stability through the process. Developing countries have no such constraints and can establish an entirely new and technology-friendly system from the start.
- Digital Demand Response Built in by Design: According to IEA, demand response via digital means is capable of reducing curtailing of variable renewable energy sources by over 25% in 2030, resulting in increased system efficiency and cost savings for consumers. Countries building their smart grids for the first time will have an opportunity to incorporate features for demand response. They can do so right from the start of construction.
- Consumer Adaptability as a Competitive Asset: The same adaptability that made M-PESA succeed has now become an even faster force for the adoption of prepaid smart meters, rooftop solar power, and peer-to-peer energy sharing in places where the existing players simply do not have the means or motivation to block innovation. As researchers at Science highlighted in 2025, African consumers have repeatedly surprised experts by successfully embracing new technologies.
What the West Must Learn and Fast
The World Resources Institute makes its position very clear: global grid investment needs to grow annually. It must rise from $410 billion in 2025 to around $600 billion in 2030. This increase is necessary for the world to achieve its climate and energy goals. The World Resources Institute also notes that financing is not the main problem. Permitting delays and fragmented regulation prevent Western grid modernisation.
The lessons emerging countries teach us are simple and replicable:
- Federal permit reforms. Western grid modernisation faces its biggest challenge in permitting rather than technology. Federal permit reforms could help address this barrier. Countries implementing national permitting reforms are able to build faster and cheaper.
- Modular solutions vs megaprojects. Developing countries are adopting modular grid solutions that offer greater flexibility for incremental upgrades, rather than relying on the large-scale, single-point-of-failure projects common in the West.
- Combine efforts in expanding supply with an equal focus on demand flexibility. Utilities can balance the grid just as effectively by managing demand and implementing demand response measures as they can by adding generation capacity, often at a lower cost. India and Brazil are developing their grids, keeping these principles in mind.
- Mirror investment in data architecture to investment in the physical grid. Mandatory local content policy applied to data meters software by India demonstrates an advanced level of understanding that data intelligence is crucially important, just like the grid’s physical infrastructure.
- Learn lessons from the leapfroggers. Kenya, Morocco, and India are implementing smart grids at scale, not through pilots. The experience accumulated by them is one of the best sources of insights on smart grids development.
The Strategic Takeaways: From the ExpertLens
- Analysts project that the global smart grid market will reach $238.63 billion by 2035. They expect it to grow at a CAGR of 17%, with emerging economies expanding their share of deployments.
- India has rolled out 47.6 million smart meters and surpassed 52% non-fossil energy capacity in early 2026. This makes India the world’s second-largest renewable energy growth market.
- State Grid of China has allocated RMB 4 trillion ($548 billion) for grid investments between 2026 and 2030. This represents a 40% increase over the previous five-year plan and sets a new global record.
- By 2050, Africa could account for up to 40% of the world’s total potential solar energy. In 34 African nations, 23% of households use electricity from off-grid sources.
- The Latin American smart meter market is projected to grow at a CAGR of 21.7%, reaching 38.4 million units by 2028. A year ago, Brazil doubled its solar energy generation capacity.
- The US will see 2,600 GW and Europe – 1,700 GW of clean energy projects stuck in grid queues; the problem is not money but regulations.
Recommendations for Stakeholders
- Grid Permitting Reform and Regulatory Approvals Process: The national governments of both the US and the EU need to approach grid permitting reform on a par with military infrastructure. Preapproved corridors, centralized federal assessments, and standardized environmental impact assessments can reduce permit times from years to months. This may be the most effective move possible.
- Learn From China and India as Peer Examples Rather Than Rivals: Western utilities and regulators should initiate structured knowledge exchange programs with organizations such as the State Grid of China and India’s National Smart Grid Mission (NSGM). Countries outside the OECD are now implementing many of the world’s most advanced large-scale grid projects.
- Emphasize the Consumer Side of Smart Grid: Utilities and policymakers should treat demand response, dynamic pricing, and bidirectional metering technologies as core grid components rather than optional enhancements. Evidence from large-scale deployments shows that consumer-side intelligence can significantly improve grid efficiency and responsiveness.
- Embrace Modularity Rather Than Monolithic Mega-Projects: Developing nations are increasingly building modular, interoperable grid systems that they can upgrade incrementally. In contrast, large monolithic projects in the West often face delays, cost overruns, and single-point vulnerabilities. Modular infrastructure offers greater resilience and adaptability.
- Establish Common Standards for Grid Data Architecture at the National Level: Interoperable and open standards for grid and smart metering data are critical for AI-driven optimization. China’s unified AMI framework and India’s emphasis on standardized data systems demonstrate the benefits of coordinated architecture. Fragmented data standards remain a structural disadvantage in Western markets.
The Smart Grid Race: Turning Global Shifts into Strategic Opportunities
There is a new grid race leaderboard, and the West is not atop it. India has reached 52% non-fossil energy capacity. Africa is leapfrogging straight to decentralized grids. Brazil increased its solar power generation capacity tenfold last year alone.
The US has 2,600 gigawatts of clean energy stalled in development queues, while Europe is sitting on 1,700 gigawatts in 16 countries. Meanwhile, Germany has managed to equip 15% of households with smart meters in a decade of effort.
While access to capital, institutional capacity, and know-how were the main factors that helped the West win the grid race. These factors helped the West lead the grid race in the past century, but will not be enough in this one. Agility and flexibility are becoming increasingly important for countries modernising their grids. So is the ability to experiment and move quickly without legacy infrastructure holding them back.
Annual investments in grids have to rise to at least $600 billion by 2030 to fight climate change. Achieving this goal will require speed and humility in learning from other countries.
Developing countries no longer aspire to achieve closed-loop grid innovation. They have learned to export it as an asset.
Expertlancing helps organisations navigate evolving technology landscapes through IP research, technology advisory, and market intelligence. Its capabilities span technology landscaping and mapping, technology scouting, competitive intelligence, and market research. By combining patent data with technical and market insights, Expertlancing helps clients track smart grid innovations and assess emerging technologies. It also helps them monitor competitor developments and identify potential opportunities across the energy sector.
Contact us to discuss your research needs and explore how our IP intelligence and technology advisory capabilities can support your next strategic decision.
About The Author